Selamat datang di Blog seputar Driver Printer PC, Laptop All Update terbaru.

Health Insurance Cancellation Laws
  

Health Insurance Cancellation Laws

Health Insurance Cancellation Laws - Individual health insurance policies are typically guaranteed renewable after a 12-month contract period between you and your insurance carrier. However, your insurance provider may choose either to continue or cancel the health coverage when the policy expires. If coverage continues, your insurer may alter your plan by increasing cost-sharing (like copays and deductibles), charging higher premiums, or reducing the covered benefits. 


But what happens when your insurer won’t continue providing coverage? Due to frivolous cancellations in the past, current law prohibits your health insurance provider from dropping you without notice. The written notice the insurer will send should give you time to find new coverage or appeal the decision. 


Learn more about when your insurer can cancel your health policy, your rights when the policy is canceled, filing an appeal, and your insurance options after cancellation. 


Key Takeaways

  • An insurance company has a right to cancel your health coverage if you fail to fulfill your obligations per the policy guidelines. 

  • Your insurance provider must serve you with a written notice before it can drop your health coverage. 

  • An insurance company can’t drop your health coverage if you made an honest mistake in your insurance application. 

  • Your state may run a consumer assistance program that helps you file an appeal or request a review of your health insurance provider’s termination decision. 

When Your Health Insurance Company Can Cancel Your Policy

Insurance companies are businesses dealing with risks, and being able to assess risks and avoid losses is part of how they operate. Their insurance policies are usually contractual agreements bound by certain rules, so they could terminate your coverage if you veer from the conditions set forth in your policy. 


Luckily, current law also limits what an insurer can include as reasons for canceling your health insurance policy. For instance, an insurer typically isn’t allowed to cancel a policy midway through its term and before its expiration or renewal date.1 Your health insurance company can legally terminate your policy on these grounds: 

  • You fail to pay premiums by the due date.
  • You voluntarily or mutually agree to end the coverage. 
  • You intentionally falsify information or provide incomplete information that’s crucial to the coverage on your insurance application. 
  • You commit fraud in obtaining insurance benefits. 
  • You’re no longer eligible for coverage through termination from employment or death. 


While an insurance company may terminate your policy for nonpayment of premiums, you may qualify for premium payment relief or a grace period during which you can settle any premiums due. The grace period for health insurance policies is as follows:1

  • At least seven days for weekly premium policies. 
  • At least 10 days for monthly premium policies.
  • At least 31 days for all other policies.

Your Rights When Your Policy Is Canceled

When your insurance policy first comes into force, an insurer may cancel it within the first 60 days without giving a reason for the cancellation. After 60 days, an insurer must provide a written policy termination notice before the policy’s expiration date. The termination notice must clearly provide the grounds for dropping your insurance.1


In the past, an insurance company could drop your insurance, void your policy, or ask you to refund the money they’ve spent on your medical bills if it found a problem with your insurance application. Fortunately, current laws now prohibit insurance companies from canceling your health coverage for making an honest mistake or leaving out information that has minimal ramifications for your health.  


Importan : When your insurance company says no to your health coverage, that doesn’t have to be the final word. You can start by appealing to the insurance company. If your coverage isn’t reinstated, you can take your appeal to an independent review organization. 


An insurance company must inform you why it ended your coverage and how you can dispute the decision. 


Filing an Appeal

You can appeal your insurer’s cancellation decision in these two ways. 


Internal Appeal

When you challenge your insurer’s decision through an internal appeal, you’re simply asking the insurance company to revisit the decision and do a full and fair review. If the appeal is urgent, your insurer must expedite the process. If your insurance company still upholds its decision, you can proceed to the second option. 


External Review

If an internal appeal fails, the law allows you to seek independent third-party intervention to review the insurance company’s decision. With an external review, the insurance company is stripped of its power to overturn the external reviewer’s decision.2


NOTE : You must request an external review within four months after the date you receive a policy termination notice from your insurer.3 


In all states, insurance companies must have and adhere to an external review process that conforms with federal consumer protection standards. This way, you’ll be protected by the guidelines of the process. If your state’s external review process doesn’t meet the consumer protection standards threshold, the U.S. Department of Health and Human Services (HHS) will oversee the review process in your state. 


You won’t incur any charges if your insurer used the HHS-administered external review process. However, you’ll be charged if your insurance company contracts with an independent review organization, but this won’t exceed $25 per review.3


Health Insurance Options After Cancellation

As mentioned, your insurer must provide notice and give clear reasons for canceling your policy. The notice period is at least 30 days and should help you appeal or seek alternative coverage.4 If an insurer rejects your appeal, you have the right to purchase any other health plan you qualify for. Here are your health insurance options if your current coverage is canceled. 


Buy Another Plan From Your Insurer

You can still apply for another health insurance plan through your current insurer as long as you’re eligible. The insurance company shouldn’t lock you out of purchasing—either directly or through an agent—any of its other plans for which you qualify. Inquire with the insurance company which plans may be available to you. 


Apply for a Marketplace Plan 

You can seek health coverage through the Marketplace or any insurer that sells insurance through the Marketplace. If you lost coverage for non-payment of premiums, you could qualify for income-based financial assistance on premiums and out-of-pocket costs. You may also be eligible for low-cost or free coverage through Medicaid or CHIP (Children’s Health Insurance Program). Marketplace plans also come with their own rights and protections. 


Buy a Plan From Another Insurer

You can purchase health insurance from another insurance company outside the Marketplace. Contact multiple companies to see what plans are available in your state and to compare prices. Most of the plans you buy outside the Marketplace will also include rights and protections. 


Enroll in any Other Coverage Available to You

If you can’t secure coverage through and outside the Marketplace, you may sign up for any other coverage your situation qualifies you for. For instance, you could enroll in an employer-sponsored group health plan, Medicare, TRICARE, or Department of Veterans Affairs (VA) health care, among other types. 


Frequently Asked Questions (FAQs)

Do current health insurance cancellation laws protect all plans?

Cancellation laws prohibiting insurers from terminating your coverage because of an oversight on your insurance application protect all Marketplace plans, including grandfathered plans. For other appeals, you’ll need to identify whether you have an individual, group, or government-sponsored plan because the protection laws may differ. 


How and when will I be notified if my health insurance policy is being canceled?

If your health insurance company is terminating your policy, it must provide at least 30 days’ notice before the policy expiration date. 


What should I do after I get a cancellation notice on my health insurance policy?

After you receive a cancellation notice, read through it to understand why coverage was terminated. If the cancellation was unfair, seek to understand the appeals process and timeline. You can start your appeal within the policy cancellation notice period.
Insurance Gas/Electricity Loans Mortgage Attorney Lawyer Donate Conference Call Degree Credit Treatment Software Classes Recovery Trading Rehab Hosting Transfer Cord Blood Claim compensation mesothelioma mesothelioma attorney Houston car accident lawyer moreno valley can you sue a doctor for wrong diagnosis doctorate in security top online doctoral programs in business educational leadership doctoral programs online car accident doctor atlanta car accident doctor atlanta accident attorney rancho Cucamonga truck accident attorney san Antonio ONLINE BUSINESS DEGREE PROGRAMS ACCREDITED online accredited psychology degree masters degree in human resources online public administration masters degree online bitcoin merchant account bitcoin merchant services compare car insurance auto insurance troy mi seo explanation digital marketing degree florida seo company fitness showrooms stamford ct how to work more efficiently seo wordpress tips meaning of seo what is an seo what does an seo do what seo stands for best seo tips google seo advice seo steps

How Long Can You Stay on Your Parent’s Health Insurance?


How Long Can You Stay on Your Parent’s Health Insurance?

How Long Can You Stay on Your Parent’s Health Insurance? - Current federal law enables you to remain on a parent’s policy up to age 26, and some state laws allow you to keep the coverage even longer.


When it’s time to get your own coverage, it’s important to know how to get a policy and understand the type of plan that will best fit your needs. Some plans offer more affordable premiums, while others pay more health care costs. But what’s most important is that you continue health insurance coverage, even if you’re young and healthy.


Key Takeaways

  • Unmarried and married children can stay on their parent’s insurance until they turn 26.
  • Some states extend the deadline indefinitely for disabled dependents.
  • Once you’re off your parent’s insurance, you have several options for health care coverage.


When You Will Lose Health Insurance Through Your Parents


Currently, the Affordable Care Act (ACA) mandates that children are covered by a parent’s health insurance plan until the child turns 26,1 if the parent’s health plan offers coverage for dependents. The rule applies to unmarried and married children and all types of health plans, including employer-sponsored coverage, according to the Department of Labor.


The law also allows you to remain on a parent’s plan if you:

  • Go to college or drop out of school
  • Adopt or have a child
  • Move out of your parents’ house
  • Are not claimed as a dependent on your parents’ tax returns
  • Refuse an offer of employer-sponsored health insurance

TIP : If your parents have coverage from the health insurance marketplace, you can remain on the policy until December 31 of the year you turn 26, or the oldest age allowed by your state’s insurance code.2


Some States Extend the Age Limit

Some states follow the ACA’s age-26 rule, but others have laws that allow you to remain on a parent’s health insurance policy longer—but only under certain conditions. Although the following states offer exceptions, health care laws are subject to repeal or revision.3


 Dependent Age Limit Exceptions

Florida Up to age 30 for unmarried dependents with no children and who live with their parents up to age 30

Georgia No age limit for disabled dependents incapable of self-sustaining employment

Idaho No age limit for disabled dependents

Illinois Up to age 30 for dependents who are veterans

Indiana No age limit for disabled dependents incapable of self-sustaining employment

Iowa No age limit for disabled dependents and full-time students

Massachusetts No age limit for disabled dependents incapable of self-sustaining employment

Minnesota No age limit for disabled dependents

Missouri No age limit for disabled dependents incapable of self-sustaining employment

Nevada No age limit for disabled dependents incapable of self-sustaining employment

New Jersey Through age 31 for unmarried dependents who have no dependents

New York Through age 29 for unmarried dependents who are residents of New York

No age limit for unmarried, disabled dependents incapable of self-sustaining employment

Ohio No age limit for disabled dependents incapable of self-sustaining employment

Oregon No age limit for disabled children and elderly parents

Pennsylvania Up to age 30 for those without dependents and are residents of Pennsylvania, or full-time students without dependents

Up to the length of deployment for full-time students who are National Guard or reservists who leave school due to deployment

Rhode Island No age limit for disabled dependents

South Carolina No age limit for disabled dependents incapable of self-sustaining employment

South Dakota Through age 29 for full-time students

No age limit for disabled dependents incapable of self-support

Wisconsin No age limit for full-time students

No age limit for full-time students who are National Guard or reservists called into active duty

No age limit for dependents called for federal active duty


Health Insurance Options for Young People 

If you have aged out and need to find new health insurance, you have a few options.


Employer-Sponsored Health Insurance

Some employers offer group health insurance plans for their employees. With a group plan, the employer chooses the plan and often pays a portion of your premium. Some group plans may limit the doctors and hospitals from which you can seek services, and you may not be able to keep the same coverage when you go to work for another employer.


In 2020, employer-sponsored coverage cost an average of $7,470 for single coverage and $21,342 for family coverage. Typically, workers pay an average of 17% of the cost for single coverage and 27% for family coverage, according to the Kaiser Family Foundation.4


The Health Insurance Marketplace

The marketplace provides health insurance tailored for people who don’t get health insurance through an employer. Many marketplace participants receive subsidies that lower their premiums. You can research and buy marketplace coverage at HealthCare.gov or through your state’s marketplace. Marketplaces allow you to apply during “open enrollment” periods that typically run from Nov. 1 to Dec. 15.5


Some insurance companies offer short-term health insurance plans that provide basic health coverage but do not comply with ACA rules. These relatively affordable plans can be a stop-gap if you aren’t eligible for marketplace plans. Beware: Short-term plans can deny coverage for preexisting conditions.


COBRA

The Consolidated Omnibus Budget Reconciliation Act (COBRA) allows workers who have employer-based health insurance to continue their benefits. COBRA coverage is only available following certain qualifying events such as job loss, reduction in work hours, death of the policyholder, or divorce from the policyholder. The ACA also dictates that COBRA coverage extends to dependent children, up to their 26th birthday.6 Although COBRA can help bridge the gap if you lose your coverage, it often requires you to pay the entire premium out of pocket.


Medicaid

Federal and state governments work together to provide Medicaid, which is health insurance available to low-income adults, elderly adults, people with disabilities, children, and pregnant women. States administer Medicaid according to federal guidelines. Eligibility for Medicaid is based on your modified adjusted gross income. To qualify, you must hold U.S. citizenship or have a qualifying non-citizen status such as permanent residency. Typically, you must be a resident in the state in which you apply for Medicaid.


School-Sponsored Health Insurance

Many colleges and universities offer health insurance policies to their students. Some school-based plans offer coverage for less than $2,000 per year, with copayments ranging from $30 for an office visit to $150 for an emergency room visit. Check with your school to find out what its plan covers.7


How Do You Choose the Right Coverage?

Before shopping for your first health insurance policy, it’s important to know the types of plans available, the level of coverage you can expect, and associated costs.


Types of Plans

The most common types of health insurance plans include:


Exclusive provider organizations (EPO): With an EPO, the plan will only cover costs if you seek the services of doctors, hospitals, and services within the defined network, except when you need emergency care.

Health maintenance organizations (HMO): HMOs contract with doctors, sometimes within a specific service area, to provide care and preventivehealth services. This type of plan only covers the cost of services provided by in-network caregivers, except in emergencies.

Point of service (POS): With a POS, you pay less for physician and hospital care when you seek services with a network. To receive specialist care, you must obtain a referral from your primary care physician.

Preferred provider organization (PPO): PPOs offer reduced-cost services when you seek care from doctors and hospitals within a network. This plan doesn’t require you to obtain a referral for specialist care.

Costs

Health insurance coverage requires you to pay a monthly premium. But you’ll also have to pay other costs when you need care.


Deductible: The deductible is the amount of money you must pay out of pocket before the policy starts covering costs.

Copayments: Fixed payments for certain services (primary care visit, specialist visit, urgent care, etc.) you make before or after you meet your deductible, depending on the plan. For example, a plan may require you to pay a $20 copayment each time you visit your doctor.

Out-of-pocket max: A health insurance plan may cap the amount of money you must pay for health care services each year. In 2021, marketplace plans cap out-of-pocket costs at $8,550 for single coverage and $17,100 for family coverage.8

Do Young People Really Need Health Insurance?

If you’re healthy, you might not think you need health insurance until you’re older. But consider this: Treatment for a broken leg can cost up to $7,500, and a hospital stay can cost $10,000 per day, according to the U.S. Centers for Medicare and Medicaid Services.9 If you don’t have health insurance, you’ll have to shoulder the entire cost of medical expenses if you sustain an injury or become ill. 


Nearly 20% of households have delinquent medical debt and about 9% of households have at one time filed bankruptcy due to health care expenses, according to a 2019 survey conducted by the Kaiser Family Foundation and the Los Angeles Times.10


Also, consider the potential for future health problems. Currently, federal law doesn’t allow ACA-compliant insurance plans to deny coverage for a preexisting condition such as diabetes or heart disease.

Insurance Gas/Electricity Loans Mortgage Attorney Lawyer Donate Conference Call Degree Credit Treatment Software Classes Recovery Trading Rehab Hosting Transfer Cord Blood Claim compensation mesothelioma mesothelioma attorney Houston car accident lawyer moreno valley can you sue a doctor for wrong diagnosis doctorate in security top online doctoral programs in business educational leadership doctoral programs online car accident doctor atlanta car accident doctor atlanta accident attorney rancho Cucamonga truck accident attorney san Antonio ONLINE BUSINESS DEGREE PROGRAMS ACCREDITED online accredited psychology degree masters degree in human resources online public administration masters degree online bitcoin merchant account bitcoin merchant services compare car insurance auto insurance troy mi seo explanation digital marketing degree florida seo company fitness showrooms stamford ct how to work more efficiently seo wordpress tips meaning of seo what is an seo what does an seo do what seo stands for best seo tips google seo advice seo steps, Insurance,Health Insurance,car insurance,auto insurance,insurance quote,car insurance quote,insurance quotes,low cost insurance,cheap insurance,cheap car insurance,cheap auto insurance,car cheapest insurance,car insurance quotes,automobile insurance,auto insurance quote,cheap car insurance quote,discount auto insurance,car insurance online,insurance rates,car insurance online quote,cheapest car insurance,donate your car sacramento,illinois asbestos attorney,new york mesothelioma lawyers,tax attorney columbus ohio,phoenix dui attorney,Keyword: donate your car sacramento,car donation san jose,donate car california,donate car sacramento,donate car,donate a car,donate car salvation army,car donation in massachusetts,car donation california,car donation,donate cars,donating car,donate car charity,donate your car,donate my car,car donation in jersey new,car donation in california,san diego car donation,donate vehicle,vehicle donations,car donation virginia,Keyword: illinois asbestos attorney,asbestos lawyer,mesothelioma attorney,mesothelioma lawyers,asbestos attorney,mesothelioma lawyer,asbestos cancer attorney,texas asbestos lawyer,houston asbestos lawyer,illinois mesothelioma lawyer,asbestos claim,mesothelioma attorneys,mesothelioma litigation,mesothelioma attorney texas,mesothelioma attorney houston,mesothelioma lawyer houston,illinois mesothelioma attorney,texas mesothelioma attorney,asbestos litigation,asbestos lawsuit,alabama lawyer mesothelioma

What Is a Preferred Provider Organization (PPO)?


What Is a Preferred Provider Organization (PPO)?

What Is a Preferred Provider Organization (PPO)? - A preferred provider organization (PPO) is a health plan where an insurance company contracts with hospitals, doctors, and clinics to create a network of participating providers. These providers have agreed to provide medical care to the plan’s subscribers at a negotiated rate. You will pay less if you use doctors, hospitals, and care providers who are in the plan’s network.


Learn more about what a PPO is, how it works, the benefits and drawbacks, and how it compares to other health plans.


PPO Definition and Examples

A PPO is an arrangement between an insurance carrier and a network of preferred providers agreeing to provide health care services at a negotiated price. Encouraging plan subscribers to use in-network providers and facilities creates a higher volume of patients, which allows for discounted rates.1 You can use hospitals, doctors, and providers outside of the network for an extra cost.


Acronym: PPO

For example, insurer Aetna offers a PPO plan that provides lower rates for doctors who are in-network, and allows you to see a doctor without a referral.2


How a PPO Works

A PPO is offered by private insurance carriers that have a network of doctors, hospitals, clinics, and other health care providers who offer medical care at discounted, negotiated fees. You’ll pay less if you use in-network (“preferred”) providers, but you have the freedom to seek health care from any doctor, hospital, or other health care provider.


NOTE : A PPO lets you schedule an appointment with any primary care doctor or specialist without a referral, and you won’t need to have a primary care physician coordinating your care.


If the doctors and facilities you use are in your PPO’s network, you will have access to discounted rates on services the plan provider has negotiated for you. Medical care from an out-of-network provider will come at a higher cost since the provider isn’t part of the pre-negotiated discount. For example, a plan might cover 80% of the cost of using a preferred provider but only cover 70% for an out-of-network provider. These percentages vary by plan and are outlined in your summary of benefits.


PPO plans typically include the following charges:


  • Premium: This is the fee your PPO plan charges each month to maintain your coverage.
  • Deductible: This is a specific annual dollar amount you must pay for covered medical services before your plan starts paying out benefits. If you enroll another family member, you’ll pay two medical deductibles: yours and another for your family members. Typically, your deductible doesn’t apply to preventive services.
  • Copay: A flat fee you pay upfront each time you see a network provider or get certain medical services. Doctor visits, hospital stays, prescription drugs, and emergency room visits often have varying copays.
  • Coinsurance: Most PPO plans will charge you a coinsurance rather than a copay, which is a percentage of the cost of covered medical services that you pay after meeting the deductible.
  • Total out-of-pocket maximum: This is the most you’ll pay in a year for covered services, which includes copays, deductibles, and coinsurance. If your out-of-pocket expenses hit this yearly maximum, your plan will pay 100% of the allowable costs for the remaining plan year.

The cost of using an out-of-network provider will depend on your PPO plan’s allowed amount or the standard rate for the service. If the provider charges you more than the allowed pricing your PPO has set, then you have to pay the difference.


Pros and Cons of a PPO

Pros

Lower costs for in-network providers

No primary care doctor needed

No referrals


Cons

More expensive

More responsibility


Pros Explained

  • Lower costs for in-network providers: A PPO network comprises doctors and facilities that have negotiated lower rates on the services they provide.
  • No primary care doctor needed: PPO plans don’t make you choose a primary care physician.
  • No referrals: In most cases, you don't need a referral to visit any doctor, specialist, or hospital. You also don’t have to consult with a primary care physician before getting a referral.


Cons Explained

  • More expensive: PPO plans are associated with higher out-of-pocket costs, including a higher monthly premium, copay, and a mandatory deductible before you can receive benefits.
  • More responsibilities: You’ll have to monitor in-network versus out-of-network providers to control costs.


PPO vs. HMO vs. EPO vs. POS

There are four basic provider networks available to customers: PPO, HMO, EPO, and POS. Each one differs in its own way.


  PPO HMO EPO POS

Premiums High Low compared to PPO Low compared to PPO Low compared to PPO

Out-of-network coverage Yes No No Yes

Referrals required No Yes Yes, for some plans Yes

Deductible Low for some plans Low High Low


PPO

A PPO health plan provides discounted medical care through a network of providers. You can also see specialists and out-of-network providers without referrals.


Health Maintenance Organization (HMO)

An HMO plan limits coverage to care and services from providers who contract with the HMO. Out-of-network care isn’t usually covered except for emergency care, and out-of-area urgent care and out-of-area dialysis for Medicare-related HMOs. You may need to work or reside in the plan’s service area to qualify for coverage. You must designate a primary care physician who coordinates all your care.


Exclusive Provider Organization (EPO)

An EPO plan only covers services and care from hospitals, doctors, or specialists who are in the plan’s network, with an exception for emergency or urgent care visits. Generally, you don’t need a primary care physician or referral to visit a specialist.


Point of Service (POS)

A POS plan is technically a combination of a PPO and HMO. It requires you to have a referral from your primary care physician to see a specialist. Coverage for out-of-network providers is also available, but with a higher copay.4


Key Takeaways

  • A PPO plan has a group of preferred or in-network providers who provide medical care at a negotiated lower rate.
  • You can visit out-of-network doctors and specialists without referrals, but at a higher cost.
  • PPO plans tend to have higher premiums and are often tied to a deductible you must pay before you start receiving benefits.
  • You or your doctor may require a preapproval from your PPO before some medical procedures, treatments, or services are performed.

Insurance Gas/Electricity Loans Mortgage Attorney Lawyer Donate Conference Call Degree Credit Treatment Software Classes Recovery Trading Rehab Hosting Transfer Cord Blood Claim compensation mesothelioma mesothelioma attorney Houston car accident lawyer moreno valley can you sue a doctor for wrong diagnosis doctorate in security top online doctoral programs in business educational leadership doctoral programs online car accident doctor atlanta car accident doctor atlanta accident attorney rancho Cucamonga truck accident attorney san Antonio ONLINE BUSINESS DEGREE PROGRAMS ACCREDITED online accredited psychology degree masters degree in human resources online public administration masters degree online bitcoin merchant account bitcoin merchant services compare car insurance auto insurance troy mi seo explanation digital marketing degree florida seo company fitness showrooms stamford ct how to work more efficiently seo wordpress tips meaning of seo what is an seo what does an seo do what seo stands for best seo tips google seo advice seo steps, Insurance,Health Insurance,car insurance,auto insurance,insurance quote,car insurance quote,insurance quotes,low cost insurance,cheap insurance,cheap car insurance,cheap auto insurance,car cheapest insurance,car insurance quotes,automobile insurance,auto insurance quote,cheap car insurance quote,discount auto insurance,car insurance online,insurance rates,car insurance online quote,cheapest car insurance,donate your car sacramento,illinois asbestos attorney,new york mesothelioma lawyers,tax attorney columbus ohio,phoenix dui attorney,Keyword: donate your car sacramento,car donation san jose,donate car california,donate car sacramento,donate car,donate a car,donate car salvation army,car donation in massachusetts,car donation california,car donation,donate cars,donating car,donate car charity,donate your car,donate my car,car donation in jersey new,car donation in california,san diego car donation,donate vehicle,vehicle donations,car donation virginia,Keyword: illinois asbestos attorney,asbestos lawyer,mesothelioma attorney,mesothelioma lawyers,asbestos attorney,mesothelioma lawyer,asbestos cancer attorney,texas asbestos lawyer,houston asbestos lawyer,illinois mesothelioma lawyer,asbestos claim,mesothelioma attorneys,mesothelioma litigation,mesothelioma attorney texas,mesothelioma attorney houston,mesothelioma lawyer houston,illinois mesothelioma attorney,texas mesothelioma attorney,asbestos litigation,asbestos lawsuit,alabama lawyer mesothelioma

How Health Insurance Works

How Health Insurance Works

How Health Insurance Works


How Health Insurance Works - Health insurance protects your assets from the high cost of medical care. But how it works can be complicated if you don't understand health insurance basics like what a deductible is, when copays apply, and how coinsurance works. Below we tackle these considerations and why health insurance is essential no matter how complicated it might seem.


Key Takeaways

  • Health insurance is a necessity for most Americans who cannot afford to pay medical bills out of pocket.
  • The cost of your health insurance premium is based on a combination of your copay, coinsurance, deductible, and maximum out-of-pocket costs.
  • The current health insurance system doesn't allow equal access to healthcare for all Americans.
  • Other countries use universal healthcare, but the Affordable Care Act only incorporates some aspects of that kind of system.


Why You Need Health Insurance

Health insurance is necessary for Americans to pay for the high cost of healthcare. You generally need it unless you can afford to pay for healthcare on your own or receive government assistance. The very wealthy can afford the cost of even extraordinary emergency or chronic medical care. Those over age 65 usually qualify for Medicare.1 Lower-income individuals and families may qualify for Medicaid.2


Everyone else must either purchase health insurance or risk medical bankruptcy. Since it is so common, many people have lost sight of its underlying purpose. It's just like insurance for your car, home, or apartment. It's supposed to protect your life savings from the devastating costs of a major accident, medical emergency, or chronic disease.


Unlike other insurance, health insurance makes it possible for you to get healthcare when you need it. If you don't have car insurance, you can take the bus until you can afford to get your car fixed. If you break your leg, you can’t splint it yourself until you save up enough to go to the doctor.


How to Choose Health Insurance


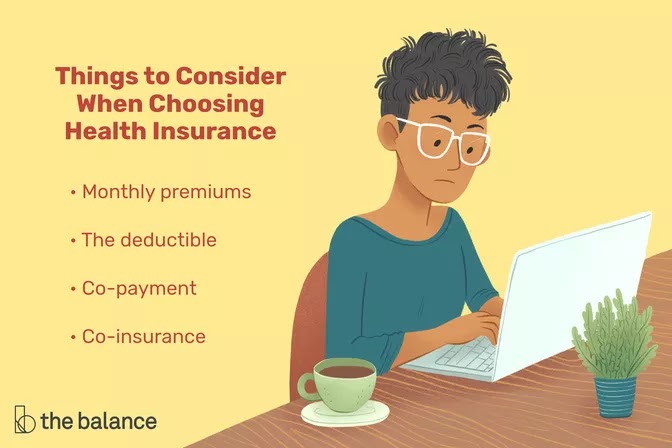
Health insurance companies provide lots of choices, options, but before you select a plan, you've got to wade through various combinations of deductibles, copays, coinsurance, and premiums. 


Monthly premiums. Like auto or homeowners insurance, you pay this even if you never make a claim. That provides the cash flow so insurance companies can pay their day-to-day expenses.

The deductible. That's what you pay before the insurance company contributes a dime. It is an annual amount, which means you start over on Jan. 1 of each year if your plan has a calendar-year policy. Plans that renew at other times of the year might not follow the calendar year for resetting the deductible period.


A copay for each visit. A typical copay might be $20 for a doctor visit, $50 for a hospital visit, and $10 to $40 for each prescription. You pay 100% for the visit until the deductible is met.3

Coinsurance. That’s a percent you pay for procedures, like surgeries, or hospital stays. If your doctor visits you in the hospital, you might pay a copayment for the visit and coinsurance for the hospitalization. 

Why do insurance companies charge deductibles, copays, and coinsurance? They want to keep you from running to the doctor for every sniffle. If healthcare were 100% free, their costs would skyrocket. The Affordable Care Act provided that these out-of-pocket costs for Marketplace plans can't exceed a maximum amount that is adjusted each year. For 2021, it was $8,550 for individuals and $17,100 for a family. For 2022, it is $8,700 for individuals and $17,400 for a family. After that, the insurance company pays 100%.4 


All of these details make picking health insurance very complicated. You’ve got to be an odds-maker on your own health. For example, you might be willing to pay a higher monthly premium for a lower coinsurance percentage and/or deductible. That would make sense if you have a chronic disease, like diabetes, and know you’ll be in to see the doctor frequently.


On the other hand, people who are healthy might want the lowest premium possible and a higher deductible. They are willing to take the chance of paying more for healthcare because they believe their risk is small. The lower the deductible, the higher the premium, copay, or coinsurance. As healthcare costs have grown, more people have opted for higher-deductible plans just to keep their monthly premiums affordable. Obamacare has not been able to correct this underlying flaw of the health insurance system.5


Why America Relies on Health Insurance to Pay for Medical Care


Before World War II, most Americans had no health insurance. The policies that existed only covered the cost of the hospital room and board. After the war, the federal government instituted a wage freeze to curb inflation, but that meant companies couldn’t give raises to get the best employees. Instead, they offered benefits, including health insurance.


In 1954, the Internal Revenue Service made health insurance premiums non-taxable.6 That made an additional dollar of health insurance more valuable than a dollar of taxable salary. The Tax Policy Center estimates that this tax break alone increased the federal deficit by $273 billion in 2019, but politicians aren’t likely to get re-elected if they suggest removing it.


This tax break is like providing a government insurance subsidy for the upper-middle classes and the wealthy. The Tax Policy Center found that the average benefit of the health insurance tax break was about $254 for a hypothetical worker in the 12% tax bracket but $347 for those in the 22% tax bracket.7 


Alternatives to Health Insurance

Many countries have adopted universal healthcare. That's where the government pays for healthcare, just like it pays for education and defense. It's like expanding Medicare or Medicaid to everyone. When Canadians go to the doctor or the hospital, the government picks up most or all of the bill. The downside is that it may take a long time to see a specialist or receive a non-emergency operation. On the other hand, no one has to worry about dying from a disease because they can't afford treatment.


When Hillarycare tried to implement universal healthcare in America, the medical profession and health insurance companies defeated it. Obamacare was initially presented as universal healthcare, but different interest groups and politicians led to that goal being changed. 


Access to healthcare has become part of today's American Dream. Research has found that the higher your income, the better your health, on average.8 As a result, income inequality has led to healthcare inequality.

Insurance Gas/Electricity Loans Mortgage Attorney Lawyer Donate Conference Call Degree Credit Treatment Software Classes Recovery Trading Rehab Hosting Transfer Cord Blood Claim compensation mesothelioma mesothelioma attorney Houston car accident lawyer moreno valley can you sue a doctor for wrong diagnosis doctorate in security top online doctoral programs in business educational leadership doctoral programs online car accident doctor atlanta car accident doctor atlanta accident attorney rancho Cucamonga truck accident attorney san Antonio ONLINE BUSINESS DEGREE PROGRAMS ACCREDITED online accredited psychology degree masters degree in human resources online public administration masters degree online bitcoin merchant account bitcoin merchant services compare car insurance auto insurance troy mi seo explanation digital marketing degree florida seo company fitness showrooms stamford ct how to work more efficiently seo wordpress tips meaning of seo what is an seo what does an seo do what seo stands for best seo tips google seo advice seo steps, Insurance,Health Insurance,car insurance,auto insurance,insurance quote,car insurance quote,insurance quotes,low cost insurance,cheap insurance,cheap car insurance,cheap auto insurance,car cheapest insurance,car insurance quotes,automobile insurance,auto insurance quote,cheap car insurance quote,discount auto insurance,car insurance online,insurance rates,car insurance online quote,cheapest car insurance,donate your car sacramento,illinois asbestos attorney,new york mesothelioma lawyers,tax attorney columbus ohio,phoenix dui attorney,Keyword: donate your car sacramento,car donation san jose,donate car california,donate car sacramento,donate car,donate a car,donate car salvation army,car donation in massachusetts,car donation california,car donation,donate cars,donating car,donate car charity,donate your car,donate my car,car donation in jersey new,car donation in california,san diego car donation,donate vehicle,vehicle donations,car donation virginia,Keyword: illinois asbestos attorney,asbestos lawyer,mesothelioma attorney,mesothelioma lawyers,asbestos attorney,mesothelioma lawyer,asbestos cancer attorney,texas asbestos lawyer,houston asbestos lawyer,illinois mesothelioma lawyer,asbestos claim,mesothelioma attorneys,mesothelioma litigation,mesothelioma attorney texas,mesothelioma attorney houston,mesothelioma lawyer houston,illinois mesothelioma attorney,texas mesothelioma attorney,asbestos litigation,asbestos lawsuit,alabama lawyer mesothelioma

Why Do I Need Health Insurance?

 Why Do I Need Health Insurance? - Health insurance is not cheap, and it can be tempting to go without coverage, especially if you never get sick. With the expensive monthly cost and out-of-pocket expenses, you may be wondering how much you really need coverage. 

Why Do I Need Health Insurance?


Many people in their 20s may feel they are healthy enough to skip out on health insurance. When you rarely see a doctor, and especially if things are tight financially, it may seem like a good idea to cut the health insurance expense completely from your budget.


You can pay for medical expenses as you go instead of worrying about the insurance premiums and co-payments on the way. However, this could be very difficult if you have a serious illness, an accident, or an ongoing health issue because the costs can become very large, very quickly. This is why it's essential for everyone to always have some form of health insurance.


Medical Emergencies Can Bankrupt You

Medical emergencies are very expensive. If you have the misfortune of undergoing a medical emergency without insurance, it is easy to find yourself with a crippling amount of medical debt, and seemingly no way out of the mess.


If you take good, preventive care of your health, it's hard to see why you'd really need insurance. However, being hit by a car and becoming seriously injured, or even just missing that last stair at home and dislocating an ankle could cause an injury that costs you thousands of dollars in medical bills, and it can quickly climb higher if you need surgery or any kind of ongoing rehabilitation. Emergency surgeries such as appendectomies can be very expensive as well.


You may not be able to work while you're laid up, and that means that you could lose out on pay as well. Even with insurance, you may find it difficult to pay for health care costs in these instances. It is very hard to pay for medical costs without health insurance, especially if you are checked into a hospital even just overnight.


Health Insurance and the Affordable Care Act (ACA)

As of 2019, you no longer have to pay a penalty on your federal tax return if you're not insured, as the fine was rescinded for the 2019 tax year, though some states may still have mandates.1


Even though there's no longer a penalty, you're protecting both your health and your financial status by taking out a health insurance policy.


You can sign up for health insurance at the Health Insurance Marketplace or a health insurance exchange in your state, or you can look at other options such as your employer's health care plan.


Preventive Care and Early Intervention

When you don't have insurance, you may avoid getting treated for minor issues, which can escalate into bigger problems quickly. Preventive medicine and quick treatment are the best ways to avoid expensive hospital stays.


If you have insurance, then you won't need to worry about this as much. Additionally, if you put off going in for treatment and wind up developing a serious medical condition, you may have a difficult time finding health insurance after you have not had any for so long.


Which Plan Fits Your Needs?

Health insurance is not a luxury; it's a necessity. There are many other things you should go without before you choose to go without health insurance.


If you want insurance but feel unsure about what coverage works for you, here are some questions you can answer to find out.

  • How's your health? Are you currently in good health, do you see a doctor regularly, and do you engage in any risky sports or occupations? Like other forms of insurance, your insurance needs are based on your degree of risk.
  • How often do you go to the doctor? Did you go several times last year and spend money on copays for office visits, lab work, urgent care, and prescription drugs? Add all of this up to get an idea of your typical annual health care needs.
  • What current options do you have? See if you can get cost-effective, quality health insurance through your employer, the Health Insurance Marketplace or your state's health care exchange, or group insurance through membership in organizations such as Costco.
  • What are your priorities? If you see the doctor often, you'll probably want a plan with lower copays and deductibles. If your monthly expenses are already straining your paycheck, perhaps you're better off with a plan that has lower monthly premiums. High-deductible plans can lower your premiums, and if you don't go to the doctor very often, it doesn't make sense to pay large premiums for a low-deductible plan.
  • What are your coverage needs? Boil down all of the available insurance plan options to those that fit your needs, then dig into the details. While the cheapest plan may grab your attention, it may not provide as much value per dollar as some other plans.
  • Have you gotten an expert opinion? Some people find the whole experience of health insurance shopping overwhelming, and there are many insurance agents that can help you sort through the options. These agents spend their days immersed in insurance and can make quick work of finding your best-fit plan. Find an independent agent who can get you quotes from a large variety of health insurance companies.


Types of Potential Health Insurance Plans

While the array of potential options is fairly complex when it comes to health insurance, plans can be categorized into a few different types.


Traditional (indemnity) or fee-for-service plans are the original type of health insurance. You can go to any doctor, hospital, or specialist you'd like, but in exchange, you'll pay more expenses out of pocket, have a deductible, and may only receive 80% coverage on remaining medical bills.


Managed Care insurance plans include Preferred Provider Organizations (PPOs), Point-of-Service (POS), and Health Maintenance Organizations (HMOs). All of these plans work only with providers in a closed network. In exchange, patients pay lower premiums and have lower or no copays. PPO and POS insurance allow patients to go to providers outside their network and self-refer to a specialist. HMOs are the lowest-cost plans, but don't pay for any out-of-network visits, and patients must be referred to specialists by their doctor.


High-deductible insurance plans, sometimes known as catastrophic plans, are much lower in cost than other insurance plans, although you'll have to pay a large amount of out-of-pocket money before coverage kicks in, so it still makes sense to put money aside each month, even if it's into your own savings account instead of paid as a premium for insurance.


In some cases, health savings accounts (HSAs) are available through these plans as well. HSAs allow you to contribute tax-deferred dollars to an account and then use those dollars to pay your deductible or other care costs.

Typically, with a high-deductible insurance plan, you will be responsible for the cost of your medical care until you satisfy the (usually large) deductible, but then the insurance plan will pick up the rest of the bills. This is still a preferable situation to going without insurance. It is much easier to find a way to pay $5,000 in medical bills as opposed to $50,000. You can often work out a payment plan for the amount you owe. This means that you won't face bankruptcy due to medical bills.

Insurance Gas/Electricity Loans Mortgage Attorney Lawyer Donate Conference Call Degree Credit Treatment Software Classes Recovery Trading Rehab Hosting Transfer Cord Blood Claim compensation mesothelioma mesothelioma attorney Houston car accident lawyer moreno valley can you sue a doctor for wrong diagnosis doctorate in security top online doctoral programs in business educational leadership doctoral programs online car accident doctor atlanta car accident doctor atlanta accident attorney rancho Cucamonga truck accident attorney san Antonio ONLINE BUSINESS DEGREE PROGRAMS ACCREDITED online accredited psychology degree masters degree in human resources online public administration masters degree online bitcoin merchant account bitcoin merchant services compare car insurance auto insurance troy mi seo explanation digital marketing degree florida seo company fitness showrooms stamford ct how to work more efficiently seo wordpress tips meaning of seo what is an seo what does an seo do what seo stands for best seo tips google seo advice seo steps, Insurance,Health Insurance,car insurance,auto insurance,insurance quote,car insurance quote,insurance quotes,low cost insurance,cheap insurance,cheap car insurance,cheap auto insurance,car cheapest insurance,car insurance quotes,automobile insurance,auto insurance quote,cheap car insurance quote,discount auto insurance,car insurance online,insurance rates,car insurance online quote,cheapest car insurance,donate your car sacramento,illinois asbestos attorney,new york mesothelioma lawyers,tax attorney columbus ohio,phoenix dui attorney,Keyword: donate your car sacramento,car donation san jose,donate car california,donate car sacramento,donate car,donate a car,donate car salvation army,car donation in massachusetts,car donation california,car donation,donate cars,donating car,donate car charity,donate your car,donate my car,car donation in jersey new,car donation in california,san diego car donation,donate vehicle,vehicle donations,car donation virginia,Keyword: illinois asbestos attorney,asbestos lawyer,mesothelioma attorney,mesothelioma lawyers,asbestos attorney,mesothelioma lawyer,asbestos cancer attorney,texas asbestos lawyer,houston asbestos lawyer,illinois mesothelioma lawyer,asbestos claim,mesothelioma attorneys,mesothelioma litigation,mesothelioma attorney texas,mesothelioma attorney houston,mesothelioma lawyer houston,illinois mesothelioma attorney,texas mesothelioma attorney,asbestos litigation,asbestos lawsuit,alabama lawyer mesothelioma

What Is an Explanation of Benefits?


What Is an Explanation of Benefits?

What Is an Explanation of Benefits? - An explanation of benefits (EOB) statement provides details about a health insurance claim that has been processed. It explains what portion was paid to the health care provider; it also tells you what portion of the payment, if any, is your responsibility.


Medical bills can be confusing. An explanation of benefits (EOB) statement can help break down the various components. If you learn how to read this important document, you'll be able to understand why you owe the charges.


Definition and Examples of an Explanation of Benefits

An explanation of benefits statement is sent to you after a health insurance claim. It lays out the details of the service, the charges from the provider, the amount covered by insurance, and how much money is still due. Each time they provide services to you, doctors, dentists, and other medical professionals will submit claims to your insurance. This is how they receive payment. In turn, the insurance company will send you an EOB. This is to inform you of the claims submitted, how much is being covered by insurance, and how much you owe.1


Any portion of the medical expense not covered by the insurance company, such as a deductible or a co-pay, will be billed by the provider. These charges should be paid directly to the provider.2


The EOB may look like a bill, but it is not. It can also be hard to make sense of. You may need to call your insurance company to ask any questions about the EOB.


The precise layout and form of the EOB will vary by insurance company. But a simple EOB will include:


A summary of your account with important identifying information and claim number.

The details of the claim, including the date and specific services provided.

The accounting, which includes the price of the service, the amount that your insurance is covering, and the difference between the two. (This is sometimes called the "adjustment," "amount allowed," or "contracted agreement.")3

An optional summary of copays, deductible, and coinsurance.

Many insurance providers, such as Blue Cross Blue Shield, will have sample EOBs available on their website. You can review them to become familiar with what EOBs look like and how the information is presented.


How an Explanation of Benefits Works

An EOB can help you avoid paying more than you should for health care. Look over an EOB when it arrives in the mail; then, compare it to your bills to ensure that you pay the correct amount. If you find an error on a bill from a doctor or other provider, call your insurance company. They will help you address the discrepancy.


What if you don't understand why you owe money or simply are having trouble reading the EOB? You can also call your insurance company or your health care provider to explain the details.


If you owe money, ask the insurance company whether this payment will be put toward your out-of-pocket deductible. Or, you may need clarification on charges for certain services, you can ask the provider to explain the services and charges for each. If you think you have been charged in error, ask the provider to go over the entire EOB, line by line. This can help you see whether a mistake occurred.


Just as health care providers can make billing errors, coding errors can occur when insurance companies process EOBs. If you do not understand something on your EOB or you think your insurance policy covers an expense that was not paid, call your insurance company for an explanation.


Importan : What if you find an error on your EOB, and the insurance company cannot fix it promptly, or if there is a disagreement? You may need to have the benefit reviewed in a more lengthy process, or file a formal dispute.


How to Get an Explanation of Benefits

The explanation of benefits statement often arrives via mail. In most cases, it closely resembles a medical bill.


Most insurance companies now provide you with online access to your account. This can include digital access to EOBs. If you don't already have online access to your account, check with your insurance company about how to get it.


Once you've set up an online account, check to see what digital access options your insurer offers. Most will let you sign up for email alerts when EOBs are available. This can allow you to view them immediately, so you won't have to wait for them to arrive in your mailbox.


Key Takeways

  • An EOB is a statement from your insurer. It outlines which portion of a claim it has paid and what portion you will have to pay.
  • You should get an EOB any time your health care provider bills your insurance.
  • Always take a close look at an EOB to be sure the charges are correct.
  • Compare EOBs to the bills you receive from providers and reconcile them before you make a payment.

Insurance Gas/Electricity Loans Mortgage Attorney Lawyer Donate Conference Call Degree Credit Treatment Software Classes Recovery Trading Rehab Hosting Transfer Cord Blood Claim compensation mesothelioma mesothelioma attorney Houston car accident lawyer moreno valley can you sue a doctor for wrong diagnosis doctorate in security top online doctoral programs in business educational leadership doctoral programs online car accident doctor atlanta car accident doctor atlanta accident attorney rancho Cucamonga truck accident attorney san Antonio ONLINE BUSINESS DEGREE PROGRAMS ACCREDITED online accredited psychology degree masters degree in human resources online public administration masters degree online bitcoin merchant account bitcoin merchant services compare car insurance auto insurance troy mi seo explanation digital marketing degree florida seo company fitness showrooms stamford ct how to work more efficiently seo wordpress tips meaning of seo what is an seo what does an seo do what seo stands for best seo tips google seo advice seo steps, Insurance,Health Insurance,car insurance,auto insurance,insurance quote,car insurance quote,insurance quotes,low cost insurance,cheap insurance,cheap car insurance,cheap auto insurance,car cheapest insurance,car insurance quotes,automobile insurance,auto insurance quote,cheap car insurance quote,discount auto insurance,car insurance online,insurance rates,car insurance online quote,cheapest car insurance,donate your car sacramento,illinois asbestos attorney,new york mesothelioma lawyers,tax attorney columbus ohio,phoenix dui attorney,Keyword: donate your car sacramento,car donation san jose,donate car california,donate car sacramento,donate car,donate a car,donate car salvation army,car donation in massachusetts,car donation california,car donation,donate cars,donating car,donate car charity,donate your car,donate my car,car donation in jersey new,car donation in california,san diego car donation,donate vehicle,vehicle donations,car donation virginia,Keyword: illinois asbestos attorney,asbestos lawyer,mesothelioma attorney,mesothelioma lawyers,asbestos attorney,mesothelioma lawyer,asbestos cancer attorney,texas asbestos lawyer,houston asbestos lawyer,illinois mesothelioma lawyer,asbestos claim,mesothelioma attorneys,mesothelioma litigation,mesothelioma attorney texas,mesothelioma attorney houston,mesothelioma lawyer houston,illinois mesothelioma attorney,texas mesothelioma attorney,asbestos litigation,asbestos lawsuit,alabama lawyer mesothelioma

Medicare vs. Medicaid: Key Differences and What Is Covered


Medicare vs. Medicaid: Key Differences and What Is Covered

Medicare vs. Medicaid: Key Differences and What Is Covered -  We publish unbiased reviews; our opinions are our own and are not influenced by payments from advertisers. Learn about our independent review process and partners in our advertiser disclosure.


In 1965, an amendment to the Social Security Act established Medicare and Medicaid, two government-run health programs.1


 Their names that sound the same may lead some people to be confused about what each program covers. Adding to the questions people have about these programs is that in some cases, people may be able to sign up for both. 


Both plans offer a few coverage options. This can make learning about them even more complex, but knowing how these programs work and differ can save you money on your health care costs.  


Learn more in our review of Medicare and Medicaid. Find out who qualifies, what's covered, and some of the key ways they differ.


If you qualify for Medicare and are ready to look at plans, eHealth Medicare, an independent insurance broker and partner of The Balance, has licensed insurance agents at 833-970-1258 TTY 711 who can help connect you with Medicare Advantage, supplement plans, and Prescription Drug Part D plans.


Key Takeaways

Medicare is mostly based on age, while Medicaid is a welfare program based on income. Its purpose is to help people with low incomes without regard to age.

Medicare Parts A and B do not include dental care, but Medicaid may cover some dental care and treatment for adults in some states.2

State Health Insurance Programs (SHIP) provide free help to teach people about programs that can help save money.

People who have Medicare may also be able to get Medicaid and use it to help pay the monthly premiums and other costs of their program.

Key Differences Between Medicare and Medicaid

A key difference between Medicare and Medicaid is that one is mainly based on age, and the other is a welfare program for people of all ages with limited financial means.


Medicare assists people 65 or older. In some cases, people under 65 with certain health concerns may be able to sign up. This only applies to the person who qualifies, but not the person's entire family.3 Medicaid is jointly run by the state and federal governments. It is for people whose eligibility is based on income rather than age or disability. It helps people and families who meet income limits get health care.4


You can apply for Medicaid at any time. You do not have to wait for an open enrollment period. In most cases, people who qualify for it may be exempt from the individual penalty. There's more on that below. When you apply for Medicare outside the time to enroll, you may have a penalty.


Differences in Dental and Vision Care

Medicare parts A and B do not include dental care like cleanings, fillings, getting teeth pulled, dentures, dental plates, or other dental items. Medicaid may cover dental care for adults in some states as well as treatment in others. This varies by state but can be a big plus over Medicare alone.


In certain cases, Medicare Part A may cover dental care if received in a hospital. Most times this would not include your standard dental care.2


Medicaid, on the other hand, only covers dental care for children.5


Eye exams or glasses may be covered by Medicaid in most states. Medicare may include a basic vision test as part of Part B care in the first preventive visit or the yearly wellness visit.


Sources to Help to Learn About Medicare and Medicaid Options

Trying to make sense of all the Medicare and Medicaid details can be a challenge. There are many programs offered, and it can be easy to get lost in the details. The good news is there are many places to get free help learning which program to sign up for. There are also other programs that you may be able to sign up for if you qualify.


State Health Insurance Assistance Programs (SHIP)

State Health Insurance Assistance Programs (SHIP) provide free, in-depth, neutral advice to help you learn about what's covered and program options which can help save you money. You can find out if there is a local SHIP office near you. You can also check out the SHIP website to get updates.


Understanding Medicaid Coverage

Medicaid may provide free or low-cost health care to people and families who meet income guidelines, people who are pregnant, seniors, and people with disabilities. More than 80 million people were covered by Medicaid/CHIP in the U.S. as of 2021.7


U.S. Medicaid rules specify certain mandatory benefits. Beyond that, each state may choose to offer extra benefits along with the basics. Because the plans are managed by each state, the state may decide the scope of the optional benefits as well as eligibility rules.


How to Get Medicaid

Medicaid differs from Medicare because it is based on finances and not age. These factors are looked at when seeing who qualifies for it:

  • Income.
  • Household size.
  • Disability.
  • Family status.

People who may be eligible for Medicaid may include: people who are pregnant, teenagers living alone, parents of sick children, people with high medical costs, blind or disabled people, or people and families with low incomes.89


Each state decides on who qualifies financially for the program. Some states that have expanded Medicaid include higher income levels in their eligibility criteria than states who have not expanded it. 


You can find out if your state is growing Medicaid and see if you qualify for it based on income or if you can get any other savings on health care.


Examples of Basic Medicaid Benefits

Below are some basic services that may be included in Medicaid.

  • Hospitalization and clinic treatment.
  • Lab and x-ray services.
  • Doctor and nursing services.
  • Medical and surgical dental services.
  • Family planning and midwife services.
  • Nursing facility services for people aged 21 or older.
  • Home healthcare for people eligible for nursing facility services.
  • Pediatric and family providers.
  • Screening, diagnosis, and treatment services for persons under age 21.10


Can You Have Medicare and Medicaid?

People who have Medicare may also get Medicaid to help pay the monthly premiums and out-of-pocket costs like deductibles of their program. If you can get both, you are deemed "dual eligible."


Medigap is an add-on health plan for Medicare that may help cover co-pays and deductibles if you can't get Medicaid.


Understanding Medicare Options

Medicare provides coverage in a few parts, with different plan options. You can have original Medicare or an Advantage Plan.


You can get Medicare from a public or private plan. Getting a plan through private insurance such as in the case of the Advantage Plan may allow you greater options in your care.


Medicare Part A covers hospital services and is free most of the time, but you may pay for it as well. For instance, if you did not work long enough to earn it, you can still get it, but you will need to pay for it.11


Medicare Part B covers medical services. There is a cost to the Part B plan.12


Medicare Parts A and B do not cover dental care, but you may be able to get covered by a supplemental health plan. 


Medicare Part C could confuse some people because it covers Parts A and B and may even include drug costs. Part C is known as the Advantage Plan. You may be able to get one of these plans that also offers vision and dental care. Be sure and check all your options when choosing one of these plans.


Medicare Part D covers prescription drugs.


If you want to access an entire list of what Medicare may cover, you can find one on the Medicare website.


How to Get Medicare: Eligibility for Parts A, B, and C

Medicare Part A: In most cases, you must be 65 years or older. You may be able to get Medicare if you are under 65 with certain conditions, end-stage renal disease, or Lou Gehrig's disease. If you are disabled and get Social Security payments for more than 24 months in a row, you may be enrolled in Medicare Part A automatically the 25th month of getting benefits.15


Medicare Part B: If you qualify for Part A, then you will have met the same rules to sign up for Part B in most cases.


Medicare Part B is optional, so make sure and sign up for it in time or you may pay a penalty for signing up after the deadline.


Medicare Part C (Medicare Advantage Plans): In order to be eligible for Part C, you must meet the rules of A and B. You can switch from a Plan A and B to a Plan C during an enrollment period.16


Medicare Savings Programs and the Extra Help Program

There are many kinds of Medicare savings programs that may help if you can't get Medicaid. It is worth looking into these to see if you qualify. You may also want to look into the Medicare Part D low income subsidy for prescription drugs: The Medicare Extra Help program. 


Get Medicaid Facts

Kaiser Family Foundation's Medicaid Pocket Primer offers detailed help and a strong look at the vital nature of the Medicaid program in the U.S. and reports on data about the people who use it.

Insurance Gas/Electricity Loans Mortgage Attorney Lawyer Donate Conference Call Degree Credit Treatment Software Classes Recovery Trading Rehab Hosting Transfer Cord Blood Claim compensation mesothelioma mesothelioma attorney Houston car accident lawyer moreno valley can you sue a doctor for wrong diagnosis doctorate in security top online doctoral programs in business educational leadership doctoral programs online car accident doctor atlanta car accident doctor atlanta accident attorney rancho Cucamonga truck accident attorney san Antonio ONLINE BUSINESS DEGREE PROGRAMS ACCREDITED online accredited psychology degree masters degree in human resources online public administration masters degree online bitcoin merchant account bitcoin merchant services compare car insurance auto insurance troy mi seo explanation digital marketing degree florida seo company fitness showrooms stamford ct how to work more efficiently seo wordpress tips meaning of seo what is an seo what does an seo do what seo stands for best seo tips google seo advice seo steps, Insurance,Health Insurance,car insurance,auto insurance,insurance quote,car insurance quote,insurance quotes,low cost insurance,cheap insurance,cheap car insurance,cheap auto insurance,car cheapest insurance,car insurance quotes,automobile insurance,auto insurance quote,cheap car insurance quote,discount auto insurance,car insurance online,insurance rates,car insurance online quote,cheapest car insurance,donate your car sacramento,illinois asbestos attorney,new york mesothelioma lawyers,tax attorney columbus ohio,phoenix dui attorney,Keyword: donate your car sacramento,car donation san jose,donate car california,donate car sacramento,donate car,donate a car,donate car salvation army,car donation in massachusetts,car donation california,car donation,donate cars,donating car,donate car charity,donate your car,donate my car,car donation in jersey new,car donation in california,san diego car donation,donate vehicle,vehicle donations,car donation virginia,Keyword: illinois asbestos attorney,asbestos lawyer,mesothelioma attorney,mesothelioma lawyers,asbestos attorney,mesothelioma lawyer,asbestos cancer attorney,texas asbestos lawyer,houston asbestos lawyer,illinois mesothelioma lawyer,asbestos claim,mesothelioma attorneys,mesothelioma litigation,mesothelioma attorney texas,mesothelioma attorney houston,mesothelioma lawyer houston,illinois mesothelioma attorney,texas mesothelioma attorney,asbestos litigation,asbestos lawsuit,alabama lawyer mesothelioma

What Does Medicare Part A Cover?


What Does Medicare Part A Cover?

What Does Medicare Part A Cover? - Medicare is the federal health insurance program that provides coverage for American citizens and permanent residents who are age 65 and older.


The original Medicare program had two parts: hospital insurance (Part A) and medical insurance (Part B). But it has expanded over the years to include optional drug coverage (Part D). Medicare can also refer to comprehensive plans offered by private companies (Part C/Medicare Advantage Plans) and supplemental plans (Medigap), also offered by private companies. First introduced in 1965, Medicare covered almost 63 million people in 2020.1


Medicare is an important part of your retirement plan. Learn the basics of what Part A does and how to sign up for it.


Key Takeaways

There are multiple parts to Medicare coverage.

Part A is hospital insurance. It also covers hospice care, plus some skilled nursing facility care and home health care.

Most people don't pay a premium for Part A coverage.

Most people are eligible to sign up for Part A and all other Medicare benefits from three months before the month they turn 65 through three months after that month.


What Is Medicare Part A?

Part A is the hospital insurance portion of Medicare. Most people become eligible for Medicare once they turn 65, and they may be automatically enrolled if they receive Social Security benefits. Otherwise, you have a limited window of time during which to sign up for Part A without having to pay a penalty. This is referred to as the initial enrollment period. It lasts for a total of seven months (three months before you become eligible for Medicare and three months after).


You won't pay a premium for Part A if you already receive Social Security retirement benefits or you're eligible for them.


NOTE : You could have a coverage gap if you wait to sign up for Medicare until the month you turn 65 or later.


What Does Medicare Part A Cover?

Part A covers a percentage of hospital or skilled nursing facilities based on benefit periods. A benefit period begins when you're admitted and ends 60 days after you're no longer receiving care. There is no limit on benefit periods. 


Part A also covers 100% of hospice care and skilled intermittent home health care.


Inpatient Care in a Hospital

What it pays for:

  • Hospital services
  • Supplies that are part of your treatment
  • Semi-private rooms
  • Nursing care
  • Drugs 
  • Meals


When it pays: Part A coverage begins when you're admitted under a physician's orders to a hospital that accepts Medicare. 


What you pay:

  • A $1,484 deductible, increasing to $1,556 in 2022, for each benefit period
  • $371 coinsurance after 61 days, increasing to $389 in 2022
  • After 91 days, $742 coinsurance for up to 60 days, increasing to $778 in 2022
  • 100% of charges once these benefits are expired3


Skilled Nursing Facility Care

What it pays for:

  • Short-term skilled nursing care
  • Occupational, speech, and physical therapy
  • Medical social services (medical social workers)
  • Dietary counseling
  • Medications
  • A semi-private room
  • Ambulance services

When it pays: After you have had a qualifying hospital stay of three days. Care ordered by a physician has to be for a qualifying condition that was treated during your hospital stay, or that began in a skilled nursing facility.


What you pay:

  • 100 days of skilled nursing care per benefit period
  • First 20 days: $0
  • Day 21 through day 100: $185.50, increasing to $194.50 in 2022
  • Day 101 and beyond: all costs


Hospice Care

What it pays for:

  • Any items, services, or durable medical equipment needed to relieve pain and manage symptoms, including drugs for pain management
  • Medical, nursing, and social services
  • Aide and homemaker services
  • Inpatient respite care received in a Medicare-certified facility to provide rest to the usual caregiver, such as a family member
  • Services can be provided in the home, or at a Medicare-certified facility. 


When it pays: A hospice doctor and your personal physician certify a life expectancy of six months or less.


What you pay:

  • $0 for care
  • $5 copay for prescriptions
  • 5% copay for the Medicare-approved amount for inpatient respite care


Home Health Care


What it pays for:

  • Part-time skilled nursing care
  • Home health aid
  • Medical social services
  • Physical, occupational, and speech therapy
  • Durable medical equipment needed for care
  • Osteoporosis injections for women

When it pays: Your physician certifies that you are homebound, puts you on a plan of care that requires one or more home health care services, and reviews that plan of care regularly.


What you pay:

  • $0 for home health care
  • 20% copay for the Medicare-approved amount for durable medical equipment


What Doesn’t Medicare Part A Cover?

No part of Medicare covers long-term care, or 24 hour-a-day custodial care. Custodial care is given at home or in a nursing home, such as a memory unit, and provides assistance with the six activities of daily living: eating, bathing, dressing, toileting, transferring, and continence. 


Medicare also does not cover dental care, dentures, eye exams for glasses, hearing aids, acupuncture, cosmetic surgery, or routine foot care.7 


Part A additionally doesn’t cover prescription drugs (other than drugs for pain management in hospice or as part of your inpatient treatment), physician fees, diagnostic services, or preventive services. 


How Part A Compares to Other Parts of Medicare

Part B

Part B is the counterpart to Medicare Part A. It covers regular exams and diagnostic services.


What it pays for:

  • Physician fees
  • Diagnostic tests
  • Preventive and screening services
  • Ambulance services
  • Durable medical equipment
  • Mental health services

When it pays: Services have to meet Medicare guidelines. Medicare publishes a guide of services covered and their maximum fees. 


What you pay: 

  • Most people pay the standard premium of $170.10 per month as of 2022.
  • High-income earners may pay up to $578.30 per month in 2022.8
  • You may have to pay an ongoing late fee if you enroll in part B after your initial enrollment period.


Part C

Part C is Medicare Advantage. It's a comprehensive health plan offered by private insurance companies. 


What it pays for: These plans have to cover at least what Medicare covers, including prescriptions, and many offer more coverage like dental and vision benefits. Medicare beneficiaries can enroll in Medicare Advantage instead of Parts A, B, and D.


When it pays: It depends on the specific plan you enroll in, but benefits eligibility will be similar to other Medicare plans.


What you pay: You must enroll and pay for the Part B premium if you select Medicare Advantage. Some Medicare Advantage plans will pay the Part B premium for you, and others will charge an additional premium. Each Medicare Advantage plan has its own deductibles and copays.9


Part D

Part D is Medicare-approved prescription drug coverage offered by private insurance companies. 


When it pays: Medicare Part D is optional. You may have to pay an ongoing penalty if you enroll in Part D after your initial enrollment period.10


What it pays for: Prescriptions have to meet plan approval for use.


What you pay: Each plan has its own premiums, copay, and deductible.


Frequently Asked Questions (FAQs)


How much does Medicare Part A cost?

There is no cost for Medicare Part A if you're eligible for Social Security benefits.


How do I sign up for Medicare Part A?

You can enroll online from the Social Security Administration website.


How is Medicare Part A financed?

Part A is financed primarily through premiums, the government’s general fund, and Medicare payroll taxes that are paid by employers and their employees.12 The withholding rate is 1.45% for employees and employers, for a total of 2.9%. An additional 0.9% is withheld on earnings above $200,000.

Insurance Gas/Electricity Loans Mortgage Attorney Lawyer Donate Conference Call Degree Credit Treatment Software Classes Recovery Trading Rehab Hosting Transfer Cord Blood Claim compensation mesothelioma mesothelioma attorney Houston car accident lawyer moreno valley can you sue a doctor for wrong diagnosis doctorate in security top online doctoral programs in business educational leadership doctoral programs online car accident doctor atlanta car accident doctor atlanta accident attorney rancho Cucamonga truck accident attorney san Antonio ONLINE BUSINESS DEGREE PROGRAMS ACCREDITED online accredited psychology degree masters degree in human resources online public administration masters degree online bitcoin merchant account bitcoin merchant services compare car insurance auto insurance troy mi seo explanation digital marketing degree florida seo company fitness showrooms stamford ct how to work more efficiently seo wordpress tips meaning of seo what is an seo what does an seo do what seo stands for best seo tips google seo advice seo steps, Insurance,Health Insurance,car insurance,auto insurance,insurance quote,car insurance quote,insurance quotes,low cost insurance,cheap insurance,cheap car insurance,cheap auto insurance,car cheapest insurance,car insurance quotes,automobile insurance,auto insurance quote,cheap car insurance quote,discount auto insurance,car insurance online,insurance rates,car insurance online quote,cheapest car insurance,donate your car sacramento,illinois asbestos attorney,new york mesothelioma lawyers,tax attorney columbus ohio,phoenix dui attorney,Keyword: donate your car sacramento,car donation san jose,donate car california,donate car sacramento,donate car,donate a car,donate car salvation army,car donation in massachusetts,car donation california,car donation,donate cars,donating car,donate car charity,donate your car,donate my car,car donation in jersey new,car donation in california,san diego car donation,donate vehicle,vehicle donations,car donation virginia,Keyword: illinois asbestos attorney,asbestos lawyer,mesothelioma attorney,mesothelioma lawyers,asbestos attorney,mesothelioma lawyer,asbestos cancer attorney,texas asbestos lawyer,houston asbestos lawyer,illinois mesothelioma lawyer,asbestos claim,mesothelioma attorneys,mesothelioma litigation,mesothelioma attorney texas,mesothelioma attorney houston,mesothelioma lawyer houston,illinois mesothelioma attorney,texas mesothelioma attorney,asbestos litigation,asbestos lawsuit,alabama lawyer mesothelioma
Back To Top